One-Time Close Construction Loans in Michigan
Build Your Dream Home With One Loan and One Closing.
Is A Non-Warrantable Condo Mortgage Right For You?
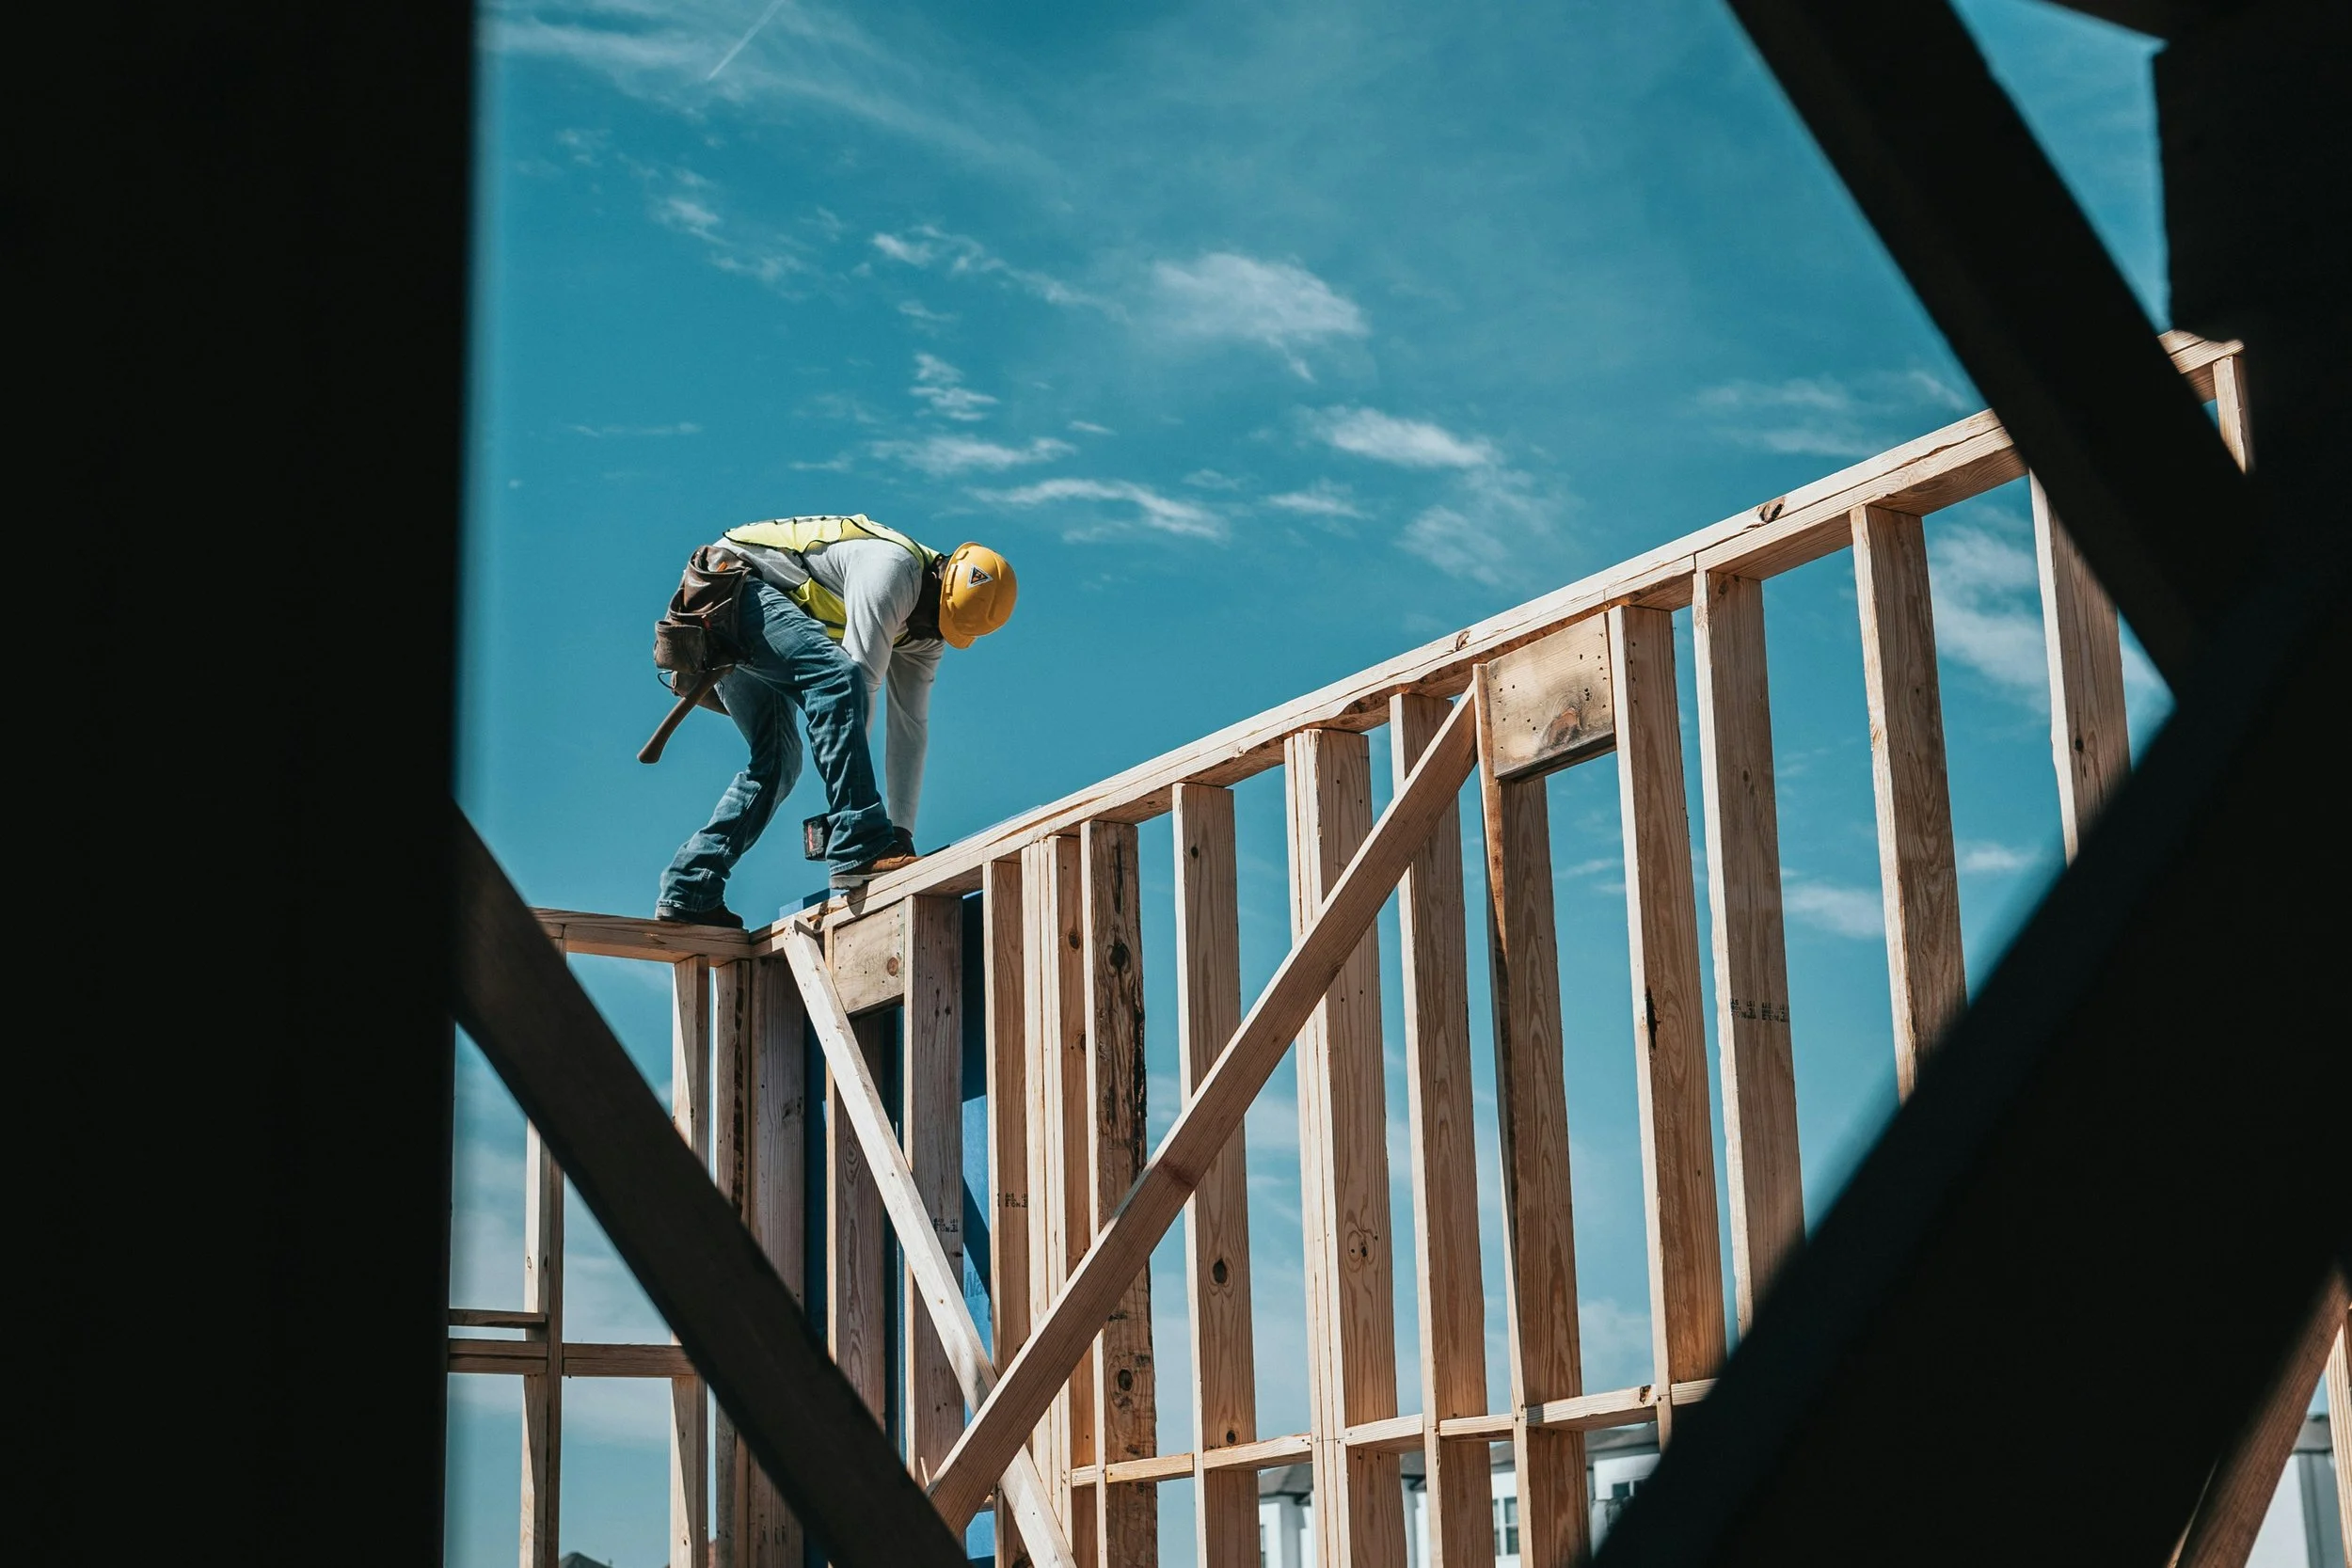
One-Time Close (OTC) Construction Loans.
Instead of obtaining one loan to build your home and another mortgage when construction is finished, a One-Time Close Construction Loan combines construction financing and permanent mortgage financing into a single transaction.
Whether you're purchasing vacant land, already own your lot, or are a Veteran planning to build your forever home, Iris Mortgage can help you explore available financing options.
One Loan. One Closing. One Step Closer to Your Dream Home.
[BUTTON: Explore My Construction Loan Options]
[BUTTON: Start My Mortgage Application]
What Is a One-Time Close Construction Loan?
A One-Time Close Construction Loan, also called a construction-to-permanent mortgage, allows eligible borrowers to finance construction and establish long-term mortgage financing with a single closing.
Traditional construction financing often requires two separate loans:
A short-term construction loan to finance the building process.
A permanent mortgage that pays off the construction loan after the home is completed.
With a One-Time Close Construction Loan, both phases are combined into one financing arrangement.
Benefits of a One-Time Close Construction Loan
One Closing: Avoid a second mortgage closing after construction.
One Loan Application: Establish construction and permanent financing through one lending process.
Potentially Lower Closing Costs: Avoid certain expenses associated with closing two separate loans.
Rate Protection: Eligible programs allow permanent mortgage terms to be established before construction begins.
Builder Coordination: Construction funds are distributed according to an approved construction draw schedule.
Flexible Land Options: Financing may be available whether you already own land or need to purchase a lot.
Fewer Financing Unknowns: Reduce the need to obtain a completely new permanent mortgage when the home is finished.
Construction-period payments, rate structures, building timelines, and other requirements depend on the selected loan program.
Conventional & VA Construction-to-Permanent Mortgage Financing
Two Construction Loan Options at Iris Mortgage
1. Conventional One-Time Close Construction Loans
Build Your Custom Home With Conventional Construction-to-Permanent Financing
Our conventional construction financing options are designed for qualifying Michigan borrowers building a new primary residence or eligible second home.
Through available lending partners, Iris Mortgage can help borrowers explore construction financing that establishes their permanent mortgage terms before building begins.
Program features may include:
Single construction and permanent loan closing
Fixed-rate and adjustable-rate mortgage options
Interest-only payments during the construction phase
Financing for eligible land purchases and new construction
Options for borrowers who already own their land
Qualifying jumbo construction financing
Construction draw management and builder review
Who Is Conventional Construction Financing Best For?
Buyers planning to build a custom primary residence
Homeowners who already own vacant land
Buyers purchasing land and hiring a builder
Eligible borrowers constructing a second home
Buyers seeking long-term financing before construction begins
Your down payment, interest rate, construction period, and borrowing limits depend on the selected mortgage program and underwriting approval.
[BUTTON: Get a Conventional Construction Loan Quote]
2. VA One-Time Close Construction Loans
Build Your Dream Home With VA Construction Financing — Potentially 0% Down
Eligible Veterans, active-duty service members, and qualifying military families may be able to finance the construction of a new home using a VA One-Time Close Construction Loan.
Iris Mortgage works with wholesale lending partners, including United Wholesale Mortgage (UWM), to explore VA construction-to-permanent mortgage options.
Instead of purchasing an existing home, eligible VA borrowers can use this financing structure to build a new home that meets their needs.
VA Construction Loan Benefits
Potentially No Down Payment: Up to 100% financing may be available for eligible borrowers and projects.
No Monthly Mortgage Payments During Construction: Under the referenced UWM VA OTC program, payments begin after construction is completed and the loan transitions to permanent financing.
One Loan Closing: Construction and permanent financing are established upfront.
No Monthly Mortgage Insurance: VA home loans do not require monthly private mortgage insurance.
Build on Land You Own: Eligible borrowers can finance new construction on an existing lot.
Purchase Land and Build: Financing may combine an eligible lot purchase with the cost of constructing the home.
Approved Builder Oversight: The builder and construction project undergo lender review before the loan closes.
An applicable VA funding fee may be required unless the borrower qualifies for an exemption.
Who May Qualify for a VA Construction Loan?
VA construction financing may be available to eligible:
Military Veterans
Active-duty service members
National Guard members
Reservists
Eligible surviving spouses
Borrowers must meet applicable VA eligibility, occupancy, income, credit, entitlement, and lender-specific construction requirements.
[BUTTON: Check My VA Construction Loan Eligibility]
VA vs. Conventional Construction Loans
Both programs can help you build your home using a single construction-to-permanent mortgage, but the financing requirements and construction-period payment structures differ.
Conventional Construction Loan
Best for: Eligible conventional borrowers building a primary residence or second home.
Down payment determined by program guidelines
Interest-only payments during construction may apply
Conventional mortgage qualification requirements
Eligible fixed-rate and adjustable-rate financing
Builder and project approval required
VA Construction Loan
Best for: Veterans and eligible military borrowers building a primary residence.
Potentially zero down payment
No monthly mortgage insurance
Under the referenced UWM program, no mortgage payments during construction
VA Certificate of Eligibility required
Builder and project approval required
Maximum 11-month construction period under the referenced UWM guidelines
Not sure which construction loan is right for you? Let Iris Mortgage review your plans, budget, land ownership, and available financing options.
[BUTTON: Compare My Construction Loan Options]
Get Your One-Time Close Construction Rate Quote Now!
Already Own Land in Michigan? You May Be Able to Use Your Equity.
If you already own a vacant lot, you may not need to start from scratch with your construction loan down payment.
Depending on the financing program, your existing land ownership and equity may help structure your construction mortgage.
Build on Land You Already Own
Eligible construction financing may allow you to:
Finance the construction of a new home on your existing property
Use qualifying land equity toward your financing requirements
Pay off an eligible existing land loan as part of the transaction
Combine eligible construction expenses into the mortgage
Establish your permanent financing before construction begins
The treatment of land equity differs between conventional and VA programs.
You may have more construction financing options than you realize—even if you have not started building yet.
[BUTTON: Review My Land and Construction Financing]
How Does a One-Time Close Construction Loan Work?
Step 1: Get Pre-Approved
Iris Mortgage reviews your income, assets, credit profile, land ownership, and estimated construction budget.
We'll help determine which construction financing options may be available for your project.
Step 2: Choose Your Builder
Work with a qualified homebuilder to finalize your plans, specifications, and construction contract.
Your builder must meet the selected lender's approval requirements.
Step 3: Submit Your Construction Project
The lender reviews your construction plans, budget, timeline, appraisal, and builder documentation.
The project must meet applicable loan program requirements before closing.
Step 4: Close Your Construction Loan
Once approved, your construction loan closes and the permanent mortgage financing is established.
If your transaction includes purchasing the land, the land acquisition may also be completed as part of the closing.
Step 5: Build Your Home
Construction begins according to the approved project schedule.
Funds are released to the builder through approved construction draws as work progresses.
Inspections and other project milestones help the lender monitor completion.
Step 6: Move Into Your New Home
When construction is complete and the required documents are received, the loan transitions to its permanent mortgage terms.
There is no separate refinance closing required under the intended One-Time Close structure.
[BUTTON: Start Building With Iris Mortgage]
What Do You Need to Qualify for a Michigan Construction Loan?
Construction loans require traditional mortgage qualification along with additional documentation related to the proposed home and builder.
Borrower Documentation
Income and employment documentation
Credit and mortgage qualification information
Bank statements and eligible asset documentation
VA Certificate of Eligibility, if applicable
Information about any land you already own
Builder and Construction Documents
Construction contract
Detailed construction budget
Building plans and specifications
Estimated construction timeline
Builder or contractor information
Property information and land contract, if applicable
Required permits and project approvals
Additional documents may be required by the lender during underwriting and construction.
You do not necessarily need to have every construction document finalized before discussing financing with Iris Mortgage.
Getting your mortgage options reviewed early may help you plan your project and avoid expensive surprises.
Michigan Homebuilders & Realtors: Partner With Iris Mortgage
Have a Buyer Who Wants to Build Instead of Buy?
Iris Mortgage works with Michigan homebuyers, Realtors, and builders to help evaluate construction-to-permanent mortgage financing.
If your client wants to purchase land and build a new home—or already owns land and needs construction financing—we can help explore conventional and VA loan options.
We can help review:
Buyer mortgage qualification
Land purchase and construction financing
Existing land equity
VA construction loan eligibility
Construction contract requirements
Builder approval processes
Construction budgets and financing structure
Before your client signs a construction contract or purchases vacant land, let Iris Mortgage review the financing options.
[BUTTON: Submit a Construction Loan Scenario]
Frequently Asked Questions About Construction Loans in Michigan
What is a One-Time Close Construction Loan?
A One-Time Close Construction Loan combines the financing used to build a new home with the permanent mortgage into one loan closing. The permanent financing is established upfront, and the loan transitions to its permanent payment terms after construction is completed.
Can I get a construction loan in Michigan with no down payment?
Eligible Veterans may qualify for VA One-Time Close Construction financing with no down payment, subject to entitlement, appraised value, underwriting, and lender requirements. Conventional construction loans generally require borrower equity or a down payment, with requirements varying by program.
Does a VA One-Time Close Construction Loan require payments during construction?
Under the referenced UWM VA One-Time Close Construction program, borrowers do not make monthly mortgage payments during construction. Mortgage payments begin after construction is completed and the loan transitions to permanent financing.
Can I use a VA loan to build a house in Michigan?
Yes. The VA allows eligible borrowers to finance construction of a qualifying home they intend to occupy as their primary residence. Participating lenders may have additional builder, property, and construction requirements.
Can I buy land and build a house with the same mortgage?
Yes. Eligible One-Time Close Construction Loan programs may allow borrowers to finance the lot purchase and home construction as part of one transaction.
Can I get a construction loan if I already own the land?
Yes. Construction financing may be available to build on land you already own. The lender will review existing land liens, property value, construction costs, and program requirements.
Can land equity count toward a construction loan down payment?
Potentially. Land equity may help satisfy financing requirements depending on how the land was acquired, its value, existing liens, and the selected loan program.
What is the difference between a construction loan and a construction-to-permanent loan?
A standalone construction loan generally funds only the building phase and requires separate permanent financing afterward. A One-Time Close construction-to-permanent loan establishes both construction and permanent financing at the beginning of the project.
Do I need a licensed or approved builder?
Construction lenders generally require builder or contractor approval, which may include reviewing experience, project history, financial information, insurance, and construction documents. Requirements vary by lender and program.
How long do I have to build my house?
The permitted construction timeline depends on the program. The referenced UWM VA One-Time Close program allows a maximum construction period of 11 months. Other construction products may allow longer timelines.
Can I build a modular or manufactured home with a construction loan?
Some construction programs permit modular or manufactured homes, subject to additional property and underwriting requirements. The referenced UWM VA program allows eligible modular and manufactured homes; the referenced Mortgage Center conventional program excludes manufactured homes.
Can I build a barndominium using a VA construction loan?
Certain unique property types, including barndominiums, may be considered under the referenced UWM VA program if the appraisal includes acceptable comparable properties demonstrating market acceptance. Eligibility must be reviewed before approval.
Can I act as my own general contractor?
Owner-builder eligibility varies by program and lender. Builder approval, project management, and construction oversight requirements must be reviewed before assuming this is permitted.
Can I finance an addition or renovation with a One-Time Close Construction Loan?
The VA program described here is intended for new construction, not renovation of an existing home. Borrowers planning a renovation or addition should ask Iris Mortgage about other available mortgage products.
Do I need to be pre-approved before buying vacant land?
It is strongly recommended. Land-only financing and construction-to-permanent mortgage financing have different requirements. Reviewing the proposed land purchase, builder, budget, and loan structure beforehand can help avoid problems.
Does Iris Mortgage offer construction loans throughout Michigan?
Iris Mortgage helps eligible Michigan borrowers explore conventional and VA construction financing for qualifying new-home projects, subject to lender, property, and underwriting requirements.
Ready to Build Your Dream Home in Michigan?
Your Dream Home Starts With the Right Financing.
Whether you're building a custom home, purchasing land, using land you already own, or exploring VA construction financing, Iris Mortgage is here to help.
One Loan. One Closing. A Home Built for You.
Let's review your construction plans and find a mortgage solution that fits your project.
[BUTTON: Apply for a Construction Loan]
[BUTTON: Discuss My Building Plans]
Iris Mortgage LLC
All loans are subject to credit approval, underwriting, program availability, lender requirements, and property eligibility. Zero-down VA financing is available only to eligible borrowers and transactions. Construction timelines, interest rates, payment obligations, loan terms, and financing options vary by program. This information is not a commitment to lend or a guarantee of financing. Include Iris Mortgage LLC's applicable NMLS, licensing, and Equal Housing Lender disclosures before publication.